Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
Tax collection at source on purchases removes duplicate withholding obligation, while trade-creditor evidence requires verification before unexplained...
Transfer-pricing comparability requires material turnover effects; adjustments must cover only associated-enterprise transactions and exclude abnormal...
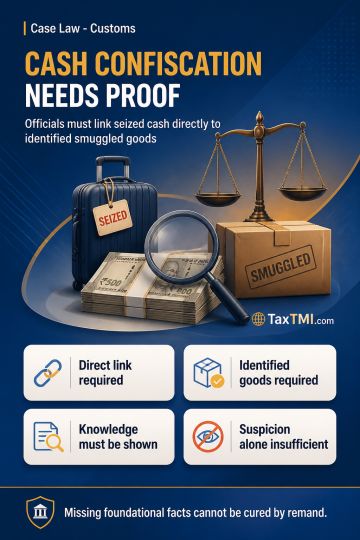
Confiscation of Indian currency alleged to represent sale proceeds of smuggled gold requires the department to prove every statutory condition. The burden-of-proof presumption applies only to specified or notified goods and does not shift the burden to a person holding seized Indian currency. Confiscation further requires proof of identified smuggled goods, their sale by a person with the requisite knowledge, and a direct, identifiable nexus between that sale and the seized currency; suspicion or an unsatisfactory explanation for cash is insufficient. Penalty likewise requires identified goods liable to confiscation and proof of the relevant knowing act or dealing. Remand cannot cure missing foundational facts or expand beyond show-cause notice allegations.
Confiscation of Indian currency alleged to represent sale proceeds of smuggled gold requires the department to prove every statutory condition. The burden-of-proof presumption applies only to specified or notified goods and does not shift the burden to a person holding seized Indian currency. Confiscation further requires proof of identified smuggled goods, their sale by a person with the requisite knowledge, and a direct, identifiable nexus between that sale and the seized currency; suspicion or an unsatisfactory explanation for cash is insufficient. Penalty likewise requires identified goods liable to confiscation and proof of the relevant knowing act or dealing. Remand cannot cure missing foundational facts or expand beyond show-cause notice allegations.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881