Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
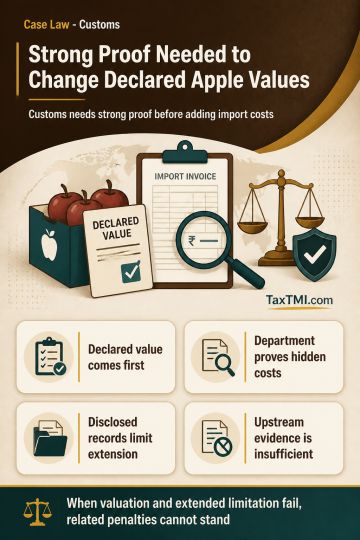
Customs valuation of CIF-imported fresh apples must begin with the declared transaction value, which may be rejected only on cogent evidence that it does not reflect the price actually paid or payable. The Department bears the burden of proving undisclosed additional consideration; an upstream FOB transaction, prepaid freight, Non-GMO certificates, and uncorroborated statements do not by themselves establish omitted freight, insurance, or a different CIF consideration. Disclosure of import documents and the CIF Incoterm precludes extended limitation absent deliberate collusion, wilful misstatement, or suppression intended to evade duty. Where valuation and extended limitation fail, enhancement, value-based confiscation, redemption fine, and related penalties cannot stand.
Customs valuation of CIF-imported fresh apples must begin with the declared transaction value, which may be rejected only on cogent evidence that it does not reflect the price actually paid or payable. The Department bears the burden of proving undisclosed additional consideration; an upstream FOB transaction, prepaid freight, Non-GMO certificates, and uncorroborated statements do not by themselves establish omitted freight, insurance, or a different CIF consideration. Disclosure of import documents and the CIF Incoterm precludes extended limitation absent deliberate collusion, wilful misstatement, or suppression intended to evade duty. Where valuation and extended limitation fail, enhancement, value-based confiscation, redemption fine, and related penalties cannot stand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881