Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Page of 4881
Press 'Enter' after typing page number.
881 to 900 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
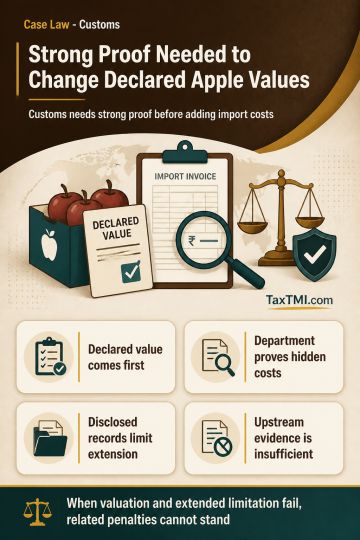
Customs valuation of CIF-imported fresh apples must begin with the declared transaction value, which may be rejected only on cogent evidence that it does not reflect the price actually paid or payable. The Department bears the burden of proving undisclosed additional consideration; an upstream FOB transaction, prepaid freight, Non-GMO certificates, and uncorroborated statements do not by themselves establish omitted freight, insurance, or a different CIF consideration. Disclosure of import documents and the CIF Incoterm precludes extended limitation absent deliberate collusion, wilful misstatement, or suppression intended to evade duty. Where valuation and extended limitation fail, enhancement, value-based confiscation, redemption fine, and related penalties cannot stand.
Customs valuation of CIF-imported fresh apples must begin with the declared transaction value, which may be rejected only on cogent evidence that it does not reflect the price actually paid or payable. The Department bears the burden of proving undisclosed additional consideration; an upstream FOB transaction, prepaid freight, Non-GMO certificates, and uncorroborated statements do not by themselves establish omitted freight, insurance, or a different CIF consideration. Disclosure of import documents and the CIF Incoterm precludes extended limitation absent deliberate collusion, wilful misstatement, or suppression intended to evade duty. Where valuation and extended limitation fail, enhancement, value-based confiscation, redemption fine, and related penalties cannot stand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881