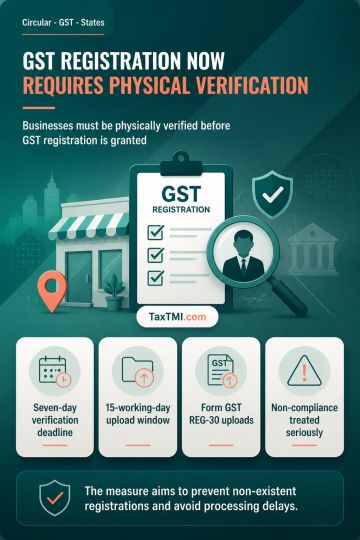
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Restoration of blocked GST portal access for furnishing Form GSTR-1 requires effective consideration of the taxpayer's supporting material. The taxpayer must submit a comprehensive representation in response to the information notice, and the competent authority must decide it through a reasoned and speaking order after granting a personal hearing. Where the material establishes that the taxpayer is a bona fide registered proprietor, the GST portal must be activated within 48 hours to enable Form GSTR-1 filing. The merits of the restoration request remain subject to fresh independent determination by the competent authority.
Restoration of blocked GST portal access for furnishing Form GSTR-1 requires effective consideration of the taxpayer's supporting material. The taxpayer must submit a comprehensive representation in response to the information notice, and the competent authority must decide it through a reasoned and speaking order after granting a personal hearing. Where the material establishes that the taxpayer is a bona fide registered proprietor, the GST portal must be activated within 48 hours to enable Form GSTR-1 filing. The merits of the restoration request remain subject to fresh independent determination by the competent authority.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881