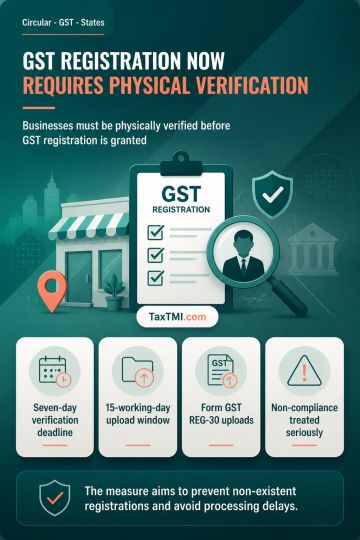
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Re-credit of excess tax to an electronic credit ledger requires examination of the taxpayer's entitlement under the applicable refund framework and CBIC circulars. Relief cannot be granted without recorded reasons; the direction permitting re-credit was therefore set aside and remanded for a fresh speaking order. Recomputation of GST liability also requires a disclosed and reasoned basis, with reference to self-assessed and auto-generated returns and audit reports on record. The unexplained reduction of assessed liability was set aside and remanded for fresh determination after hearing both sides.
Re-credit of excess tax to an electronic credit ledger requires examination of the taxpayer's entitlement under the applicable refund framework and CBIC circulars. Relief cannot be granted without recorded reasons; the direction permitting re-credit was therefore set aside and remanded for a fresh speaking order. Recomputation of GST liability also requires a disclosed and reasoned basis, with reference to self-assessed and auto-generated returns and audit reports on record. The unexplained reduction of assessed liability was set aside and remanded for fresh determination after hearing both sides.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881