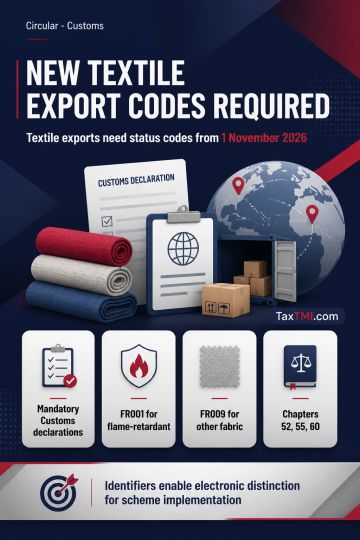
Mandatory textile export qualifiers distinguish flame-retardant fabrics from other listed fabrics for automated identification under the textiles ince...
Personal liberty safeguards restrict arrest after court-directed GST appearance, requiring interim release where authorities overreach pending proceed...
Alternative statutory remedy and delay bar GST writ challenges despite pending rectification, while distinct subject matter permits parallel proceedin...
Discretion to condone delay in filing a revised return may be exercised where revisions to tax-reporting information result in the same interest income being taxed in two assessment years. Genuine hardship must be assessed from the surrounding facts rather than a fixed formula. Double taxation, prompt pursuit of rectification remedies and absence of taxpayer inaction supported relief, while refusal would result in unjust enrichment. Permission to file the revised return was granted, subject to verification of the relevant facts and an appropriate decision in accordance with law.
Discretion to condone delay in filing a revised return may be exercised where revisions to tax-reporting information result in the same interest income being taxed in two assessment years. Genuine hardship must be assessed from the surrounding facts rather than a fixed formula. Double taxation, prompt pursuit of rectification remedies and absence of taxpayer inaction supported relief, while refusal would result in unjust enrichment. Permission to file the revised return was granted, subject to verification of the relevant facts and an appropriate decision in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935