Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
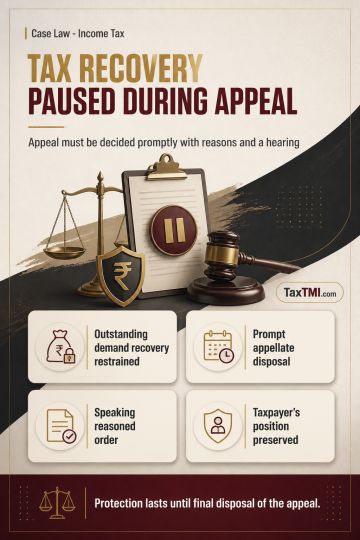
Recovery of an outstanding demand may be restrained while a statutory appeal remains pending, alongside directions for prompt appellate disposal. The appellate authority is required to decide the appeal within the stipulated period by a speaking and reasoned order after giving the taxpayer an opportunity of hearing. Interim protection against recovery continues until final disposal of the appeal, preserving the taxpayer's position pending the appellate decision.
Recovery of an outstanding demand may be restrained while a statutory appeal remains pending, alongside directions for prompt appellate disposal. The appellate authority is required to decide the appeal within the stipulated period by a speaking and reasoned order after giving the taxpayer an opportunity of hearing. Interim protection against recovery continues until final disposal of the appeal, preserving the taxpayer's position pending the appellate decision.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881