E-filing system failure permits exclusion of affected time in insolvency appeals, preventing tribunal technology defects from defeating timely filings...
Pre-existing disputes over outcome-based professional fees can bar Section 9 insolvency proceedings where contractual entitlement requires investigati...
Corresponding scheduled offences preserve money-laundering jurisdiction despite repeal of the central corruption provision where conduct remains cover...
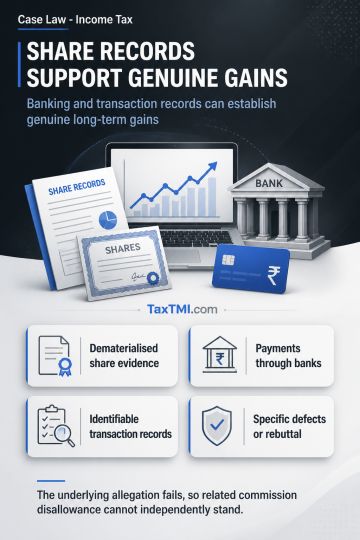
Genuineness of dematerialised equity-share transactions supporting a long-term capital-gains claim depends on documentary evidence, banking-channel payments and identifiable transaction records. Where taxpayers produce such evidence, an allegation that share-sale proceeds constitute unexplained cash credit requires specific defects or rebuttal of the material. An alleged commission expenditure linked solely to the asserted bogus share-sale proceeds is consequential and cannot independently sustain disallowance where the underlying allegation fails.
Genuineness of dematerialised equity-share transactions supporting a long-term capital-gains claim depends on documentary evidence, banking-channel payments and identifiable transaction records. Where taxpayers produce such evidence, an allegation that share-sale proceeds constitute unexplained cash credit requires specific defects or rebuttal of the material. An alleged commission expenditure linked solely to the asserted bogus share-sale proceeds is consequential and cannot independently sustain disallowance where the underlying allegation fails.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929