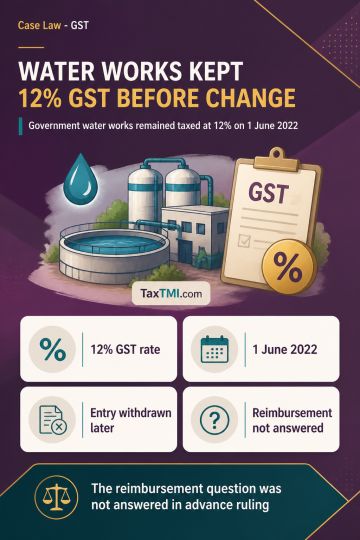
Government water works contract GST concession applied before its withdrawal, while contractual tax reimbursement claims lay outside advance-ruling sc...
Page of 4927
Press 'Enter' after typing page number.
1241 to 1260 of 98535 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Characterisation of losses on transfer of real-estate allotment rights depends on their actual treatment and supporting evidence, not book entries alone. Where the rights were recorded as short-term loans and advances rather than closing stock, and the claimed business loss was not substantiated, they were treated as capital assets. The resulting loss remained eligible for indexation and carry-forward as long-term capital loss. Where interest is claimed as part of acquisition cost, conflicting positions require fresh computation after the taxpayer is given an opportunity to provide supporting evidence.
Characterisation of losses on transfer of real-estate allotment rights depends on their actual treatment and supporting evidence, not book entries alone. Where the rights were recorded as short-term loans and advances rather than closing stock, and the claimed business loss was not substantiated, they were treated as capital assets. The resulting loss remained eligible for indexation and carry-forward as long-term capital loss. Where interest is claimed as part of acquisition cost, conflicting positions require fresh computation after the taxpayer is given an opportunity to provide supporting evidence.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927