Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review...
Bail conditions in customs-duty evasion investigation permit continued inquiry while addressing evidence-tampering concerns through procedural safegua...
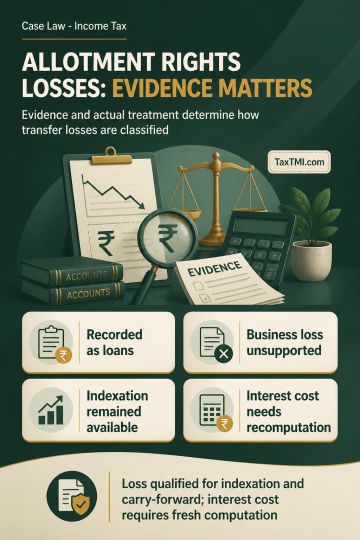
Characterisation of losses on transfer of real-estate allotment rights depends on their actual treatment and supporting evidence, not book entries alone. Where the rights were recorded as short-term loans and advances rather than closing stock, and the claimed business loss was not substantiated, they were treated as capital assets. The resulting loss remained eligible for indexation and carry-forward as long-term capital loss. Where interest is claimed as part of acquisition cost, conflicting positions require fresh computation after the taxpayer is given an opportunity to provide supporting evidence.
Characterisation of losses on transfer of real-estate allotment rights depends on their actual treatment and supporting evidence, not book entries alone. Where the rights were recorded as short-term loans and advances rather than closing stock, and the claimed business loss was not substantiated, they were treated as capital assets. The resulting loss remained eligible for indexation and carry-forward as long-term capital loss. Where interest is claimed as part of acquisition cost, conflicting positions require fresh computation after the taxpayer is given an opportunity to provide supporting evidence.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881