Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
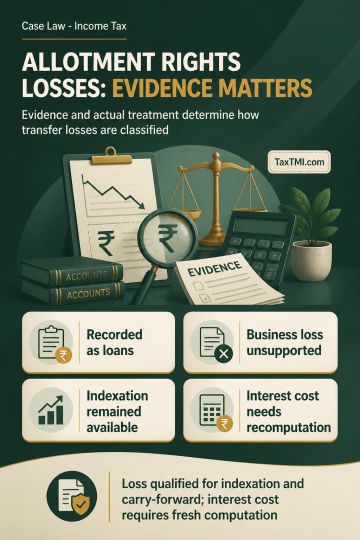
Characterisation of losses on transfer of real-estate allotment rights depends on their actual treatment and supporting evidence, not book entries alone. Where the rights were recorded as short-term loans and advances rather than closing stock, and the claimed business loss was not substantiated, they were treated as capital assets. The resulting loss remained eligible for indexation and carry-forward as long-term capital loss. Where interest is claimed as part of acquisition cost, conflicting positions require fresh computation after the taxpayer is given an opportunity to provide supporting evidence.
Characterisation of losses on transfer of real-estate allotment rights depends on their actual treatment and supporting evidence, not book entries alone. Where the rights were recorded as short-term loans and advances rather than closing stock, and the claimed business loss was not substantiated, they were treated as capital assets. The resulting loss remained eligible for indexation and carry-forward as long-term capital loss. Where interest is claimed as part of acquisition cost, conflicting positions require fresh computation after the taxpayer is given an opportunity to provide supporting evidence.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881