Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
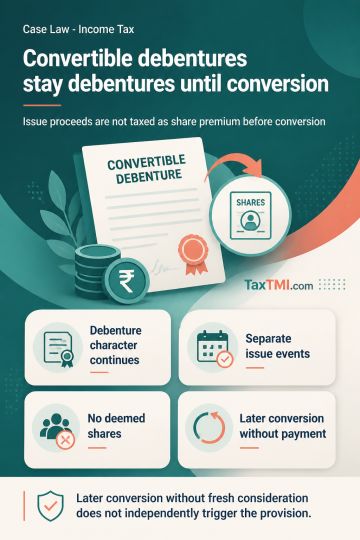
Section 56(2)(viib) applies when consideration is received for the issue of shares. Fully and compulsorily convertible debentures retain their character as debentures until conversion; compulsory future conversion does not treat them as shares on the date consideration is received. Neither section 56(2)(viib) nor Rule 11UA creates a deeming rule that classifies unconverted FCCDs as shares. The original issue of convertible debentures and the later issue of shares on conversion are distinct events, and conversion without fresh consideration does not independently trigger the provision. Regulatory or insolvency classifications cannot expand the charging language of the Income-tax Act.
Section 56(2)(viib) applies when consideration is received for the issue of shares. Fully and compulsorily convertible debentures retain their character as debentures until conversion; compulsory future conversion does not treat them as shares on the date consideration is received. Neither section 56(2)(viib) nor Rule 11UA creates a deeming rule that classifies unconverted FCCDs as shares. The original issue of convertible debentures and the later issue of shares on conversion are distinct events, and conversion without fresh consideration does not independently trigger the provision. Regulatory or insolvency classifications cannot expand the charging language of the Income-tax Act.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881