GST payment representations require record-based, reasoned decisions while substantive entitlement remains open for determination by competent authori...
Reassessment sanction under extended limitation required approval from the competent specified authority, invalidating proceedings approved by an inco...
Internal CUP benchmarking for fixed-rate Masala Bonds prevails over floating external comparables, eliminating the related transfer-pricing adjustment...
Page of 4881
Press 'Enter' after typing page number.
981 to 1000 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Chapter X confines transfer-pricing adjustments to income from...
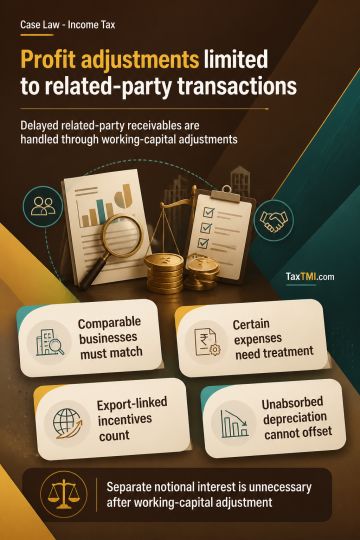
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capital adjustments.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Chapter X confines transfer-pricing adjustments to income from international transactions with associated enterprises and does not permit entity-level enhancement of profits from unrelated-party dealings. Under TNMM, operating margins must reflect appropriate treatment of non-operating marketing and promotional expenses, warranty provisions and bad debts, while business liability write-backs and export incentives linked to export sales are operating income; other operating income must not be excluded twice. Comparable selection for Air Handling Unit manufacturers depends on functional similarity, retaining industrial HVAC and refrigeration manufacturers but excluding final consumer, commercial refrigeration, or mobility-product businesses. Delayed associated-enterprise receivables linked to goods sales require combined benchmarking; a working-capital adjustment removes the need for separate notional interest. Brought-forward unabsorbed depreciation cannot be set off against income from other sources.
Chapter X confines transfer-pricing adjustments to income from international transactions with associated enterprises and does not permit entity-level enhancement of profits from unrelated-party dealings. Under TNMM, operating margins must reflect appropriate treatment of non-operating marketing and promotional expenses, warranty provisions and bad debts, while business liability write-backs and export incentives linked to export sales are operating income; other operating income must not be excluded twice. Comparable selection for Air Handling Unit manufacturers depends on functional similarity, retaining industrial HVAC and refrigeration manufacturers but excluding final consumer, commercial refrigeration, or mobility-product businesses. Delayed associated-enterprise receivables linked to goods sales require combined benchmarking; a working-capital adjustment removes the need for separate notional interest. Brought-forward unabsorbed depreciation cannot be set off against income from other sources.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881