Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
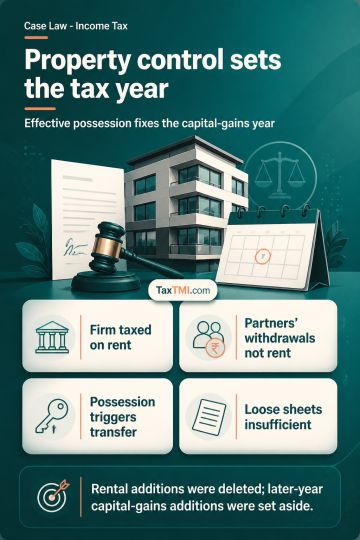
Rental receipts credited, accounted for and assessed in a registered partnership firm's hands remain taxable to the firm; partners' capital-account withdrawals do not constitute rental income or transfer ownership of the building. Under a registered joint development agreement granting the developer effective possession, dominion and authority over the property, transfer occurs on execution of the agreement rather than on later delivery of constructed area. The special capital-gains regime for joint development agreements operates prospectively and does not apply to earlier transactions. Rough, unparticularised loose sheets without independent corroboration cannot support additions for undisclosed or underreported rental income. The rental-income additions were deleted and later-year capital-gains additions were set aside.
Rental receipts credited, accounted for and assessed in a registered partnership firm's hands remain taxable to the firm; partners' capital-account withdrawals do not constitute rental income or transfer ownership of the building. Under a registered joint development agreement granting the developer effective possession, dominion and authority over the property, transfer occurs on execution of the agreement rather than on later delivery of constructed area. The special capital-gains regime for joint development agreements operates prospectively and does not apply to earlier transactions. Rough, unparticularised loose sheets without independent corroboration cannot support additions for undisclosed or underreported rental income. The rental-income additions were deleted and later-year capital-gains additions were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881