Withdrawal of obsolete FEMA circulars streamlines rules on external commercial borrowings, non-resident bond investments, and money transfer sub-agent...
Departmental appeal limitation after call-book recall preserves original filing, while documented correlation supports SAD refund on imported granules...
Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Page of 4881
Press 'Enter' after typing page number.
881 to 900 of 97618 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
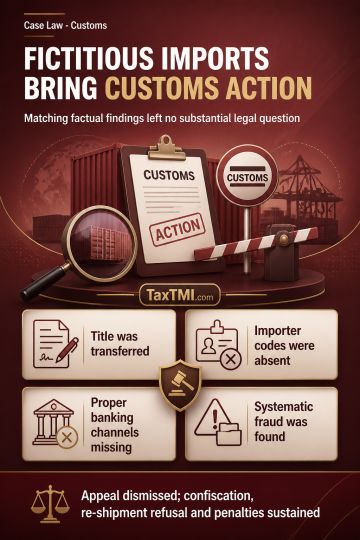
Concurrent factual findings established that the appellant had transferred title to the imported goods and was not their owner. The goods were consigned to fictitious importing firms lacking importer-exporter codes and were routed without proper banking channels, supporting findings of systematic fraud and illegal importation. These factual findings warranted confiscation and penalty and did not raise a substantial question of law. Confiscation, refusal of re-shipment and penalty were sustained, and the customs appeal was dismissed.
Concurrent factual findings established that the appellant had transferred title to the imported goods and was not their owner. The goods were consigned to fictitious importing firms lacking importer-exporter codes and were routed without proper banking channels, supporting findings of systematic fraud and illegal importation. These factual findings warranted confiscation and penalty and did not raise a substantial question of law. Confiscation, refusal of re-shipment and penalty were sustained, and the customs appeal was dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881