Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
Medical relief includes mobile healthcare services delivered to...
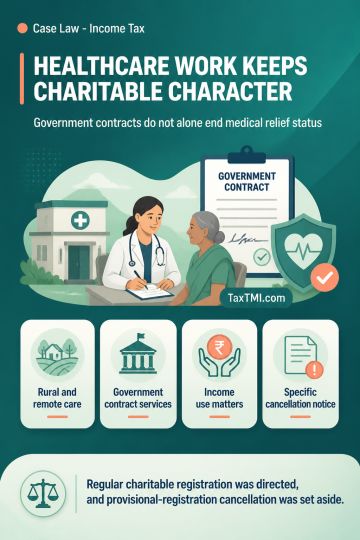
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation requires specific notice.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Medical relief includes mobile healthcare services delivered to rural and remote populations under Government contracts where the objects remain exclusively charitable and prohibit commercial operation. Contractual receipts, tax deduction at source and surplus generation do not alone convert such activities into business; the decisive considerations are the institution's purpose and deployment of income. Regular charitable registration cannot be refused merely because beneficiary records are held by the Government or payments are made to related persons, absent proof that payments were excessive or unreasonable for services rendered. Cancellation of provisional registration requires specific notice of the statutory ground and an effective opportunity to respond. Regular registration was directed, and the provisional-registration cancellation was set aside.
Medical relief includes mobile healthcare services delivered to rural and remote populations under Government contracts where the objects remain exclusively charitable and prohibit commercial operation. Contractual receipts, tax deduction at source and surplus generation do not alone convert such activities into business; the decisive considerations are the institution's purpose and deployment of income. Regular charitable registration cannot be refused merely because beneficiary records are held by the Government or payments are made to related persons, absent proof that payments were excessive or unreasonable for services rendered. Cancellation of provisional registration requires specific notice of the statutory ground and an effective opportunity to respond. Regular registration was directed, and the provisional-registration cancellation was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881