Charitable sports promotion: sponsorship receipts alone did not defeat registration where funds supported tournaments and player development activitie...
Overdue associated-enterprise receivables: debt-free status defeated notional-interest adjustment, while employee stock-option costs qualified as busi...
Retrospective assessment-limitation amendments validate final orders while contemporaneous segment data governs transfer-pricing comparability and tol...
Transfer pricing adjustments must track international transactions, while unsupported AMP adjustments and unsuitable manufacturing comparables require...
Transfer-pricing adjustments must reflect functional comparability, working-capital effects, and avoid duplicating interest on associated-enterprise r...
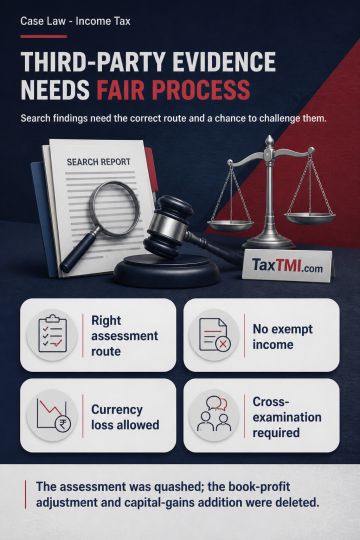
Search material found at a third party's premises must be used for assessment or reassessment under section 153C, not a regular section 143(3) assessment; where the relevant assessment was pending and abated, the section 143(3) assessment was invalid and quashed. Section 14A read with rule 8D does not permit expenditure disallowance without exempt income, and the corresponding book-profit adjustment was deleted. Foreign-exchange loss on revenue-account liabilities, recognised under Accounting Standard-11, is allowable as business expenditure. An addition based solely on undisclosed third-party material, without disclosure or cross-examination, breaches natural justice; search presumptions do not apply against the assessee, and the capital-gains addition was deleted.
Search material found at a third party's premises must be used for assessment or reassessment under section 153C, not a regular section 143(3) assessment; where the relevant assessment was pending and abated, the section 143(3) assessment was invalid and quashed. Section 14A read with rule 8D does not permit expenditure disallowance without exempt income, and the corresponding book-profit adjustment was deleted. Foreign-exchange loss on revenue-account liabilities, recognised under Accounting Standard-11, is allowable as business expenditure. An addition based solely on undisclosed third-party material, without disclosure or cross-examination, breaches natural justice; search presumptions do not apply against the assessee, and the capital-gains addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881