Effective hearing in GST adjudication requires actual opportunity to respond; ineffective service through a former auditor invalidated ex parte procee...
Third-party search material requires special assessment route, rendering general reassessment notices without jurisdiction when it forms the proceedin...
Transfer-pricing adjustments must be confined to international associated-enterprise transactions, while functionally dissimilar comparables remain ex...
Insolvency moratorium bars income-tax revision proceedings against corporate debtors until the moratorium ends, preserving merits for later determinat...
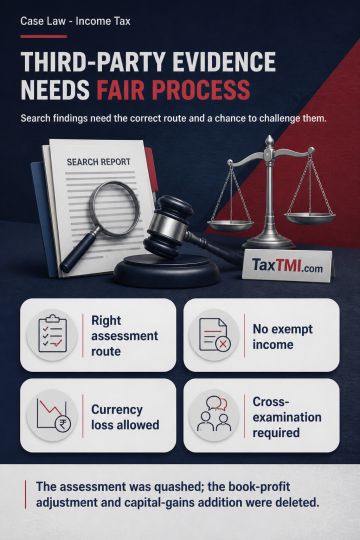
Search material found at a third party's premises must be used for assessment or reassessment under section 153C, not a regular section 143(3) assessment; where the relevant assessment was pending and abated, the section 143(3) assessment was invalid and quashed. Section 14A read with rule 8D does not permit expenditure disallowance without exempt income, and the corresponding book-profit adjustment was deleted. Foreign-exchange loss on revenue-account liabilities, recognised under Accounting Standard-11, is allowable as business expenditure. An addition based solely on undisclosed third-party material, without disclosure or cross-examination, breaches natural justice; search presumptions do not apply against the assessee, and the capital-gains addition was deleted.
Search material found at a third party's premises must be used for assessment or reassessment under section 153C, not a regular section 143(3) assessment; where the relevant assessment was pending and abated, the section 143(3) assessment was invalid and quashed. Section 14A read with rule 8D does not permit expenditure disallowance without exempt income, and the corresponding book-profit adjustment was deleted. Foreign-exchange loss on revenue-account liabilities, recognised under Accounting Standard-11, is allowable as business expenditure. An addition based solely on undisclosed third-party material, without disclosure or cross-examination, breaches natural justice; search presumptions do not apply against the assessee, and the capital-gains addition was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881