Section 153C requires person-specific search authority and year-specific incriminating material for unabated assessments while preventing unsupported ...
Equivalent-value attachment can reach pre-existing assets, but jointly owned property remains protected beyond the accused's attributable proceeds of ...
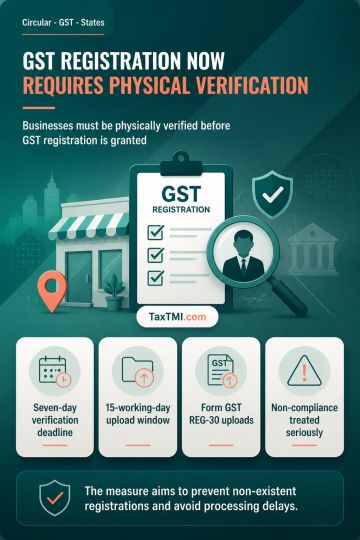
Pre-registration physical verification becomes mandatory to prevent non-existent business registrations and support timely GST registration processing...
Page of 4925
Press 'Enter' after typing page number.
1621 to 1640 of 98494 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Section 75(4) of the GST law requires the proper officer to provide a personal hearing before passing an adverse adjudication order, even where the taxable person has not requested one. Notice of a specific date, time and venue is necessary to satisfy that requirement. A hearing recorded before issue of the show-cause notice does not cure the failure to provide a post-notice opportunity. Non-compliance with the mandatory hearing requirement invalidates the adjudication and requires fresh consideration after allowing a response to the show-cause notice and conducting a properly notified hearing.
Section 75(4) of the GST law requires the proper officer to provide a personal hearing before passing an adverse adjudication order, even where the taxable person has not requested one. Notice of a specific date, time and venue is necessary to satisfy that requirement. A hearing recorded before issue of the show-cause notice does not cure the failure to provide a post-notice opportunity. Non-compliance with the mandatory hearing requirement invalidates the adjudication and requires fresh consideration after allowing a response to the show-cause notice and conducting a properly notified hearing.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4925