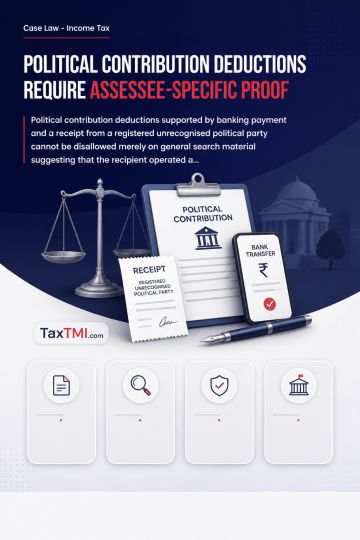
Political contribution deductions require assessee-specific proof before cash-back allegations can justify disallowance or unexplained-money additions...
Page of 4883
Press 'Enter' after typing page number.
1101 to 1120 of 97649 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
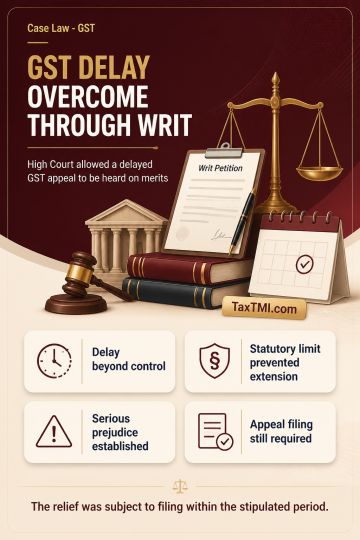
Statutory limitation for GST appeals under section 107 bound the appellate authority, but the High Court condoned delay where circumstances beyond the taxpayer's control prevented timely filing and refusal of merits review would cause grave injury and prejudice. The appellate order dismissing the appeal as time-barred was set aside. The GST appeal concerning alleged wrongful availment of input tax credit was permitted to be filed and decided on merits without limitation objection, subject to compliance with the filing period stipulated by the High Court.
Statutory limitation for GST appeals under section 107 bound the appellate authority, but the High Court condoned delay where circumstances beyond the taxpayer's control prevented timely filing and refusal of merits review would cause grave injury and prejudice. The appellate order dismissing the appeal as time-barred was set aside. The GST appeal concerning alleged wrongful availment of input tax credit was permitted to be filed and decided on merits without limitation objection, subject to compliance with the filing period stipulated by the High Court.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4883