Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
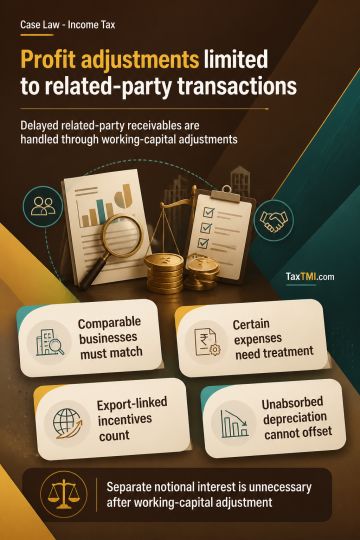
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Telecommunication-business tax treatment covers the timing and scope of deductions, revenue expenditure and transfer-pricing adjustments. Profits eligible for the telecommunication undertaking deduction include receipts with an integral business nexus, while Service from India Scheme incentives are excluded; the initial deduction year depends on when the claim was actually allowed. Annual telecom licence fees are subject to statutory amortisation rather than revenue deduction, whereas spectrum-use charges, ordinary advertising costs, subscriber-fraud losses and certain asset-restoration costs may be revenue expenditure. Automated domestic roaming payments and pre-paid distributor discounts do not require tax deduction at source. Brand-royalty and advertisement, marketing and promotion adjustments cannot rest on commercial-necessity objections or the bright-line test without a demonstrable international transaction.
Telecommunication-business tax treatment covers the timing and scope of deductions, revenue expenditure and transfer-pricing adjustments. Profits eligible for the telecommunication undertaking deduction include receipts with an integral business nexus, while Service from India Scheme incentives are excluded; the initial deduction year depends on when the claim was actually allowed. Annual telecom licence fees are subject to statutory amortisation rather than revenue deduction, whereas spectrum-use charges, ordinary advertising costs, subscriber-fraud losses and certain asset-restoration costs may be revenue expenditure. Automated domestic roaming payments and pre-paid distributor discounts do not require tax deduction at source. Brand-royalty and advertisement, marketing and promotion adjustments cannot rest on commercial-necessity objections or the bright-line test without a demonstrable international transaction.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881