Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
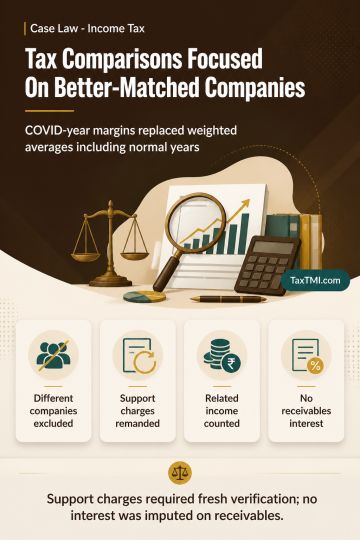
TNMM benchmarking required exclusion of functionally dissimilar, diversified, and unsegmented companies from the comparable set for manufacturing and engineering-estimation segments. Intra-group support-service charges required fresh verification of evidence showing benefits received and benchmarking under TNMM; the issue was remanded. Business-connected reversals, miscellaneous income, foreign-exchange gains and export incentives were treated as operating income where related expenditure had been treated as operating, increasing the profit level indicator. In the extraordinary COVID-affected year, current-year margins of final comparables were required for comparison rather than weighted averages including normal years. Interest on overdue associated-enterprise receivables was not imputable where audited accounts showed the taxpayer was debt-free and lease liabilities were not borrowings.
TNMM benchmarking required exclusion of functionally dissimilar, diversified, and unsegmented companies from the comparable set for manufacturing and engineering-estimation segments. Intra-group support-service charges required fresh verification of evidence showing benefits received and benchmarking under TNMM; the issue was remanded. Business-connected reversals, miscellaneous income, foreign-exchange gains and export incentives were treated as operating income where related expenditure had been treated as operating, increasing the profit level indicator. In the extraordinary COVID-affected year, current-year margins of final comparables were required for comparison rather than weighted averages including normal years. Interest on overdue associated-enterprise receivables was not imputable where audited accounts showed the taxpayer was debt-free and lease liabilities were not borrowings.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4929