Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
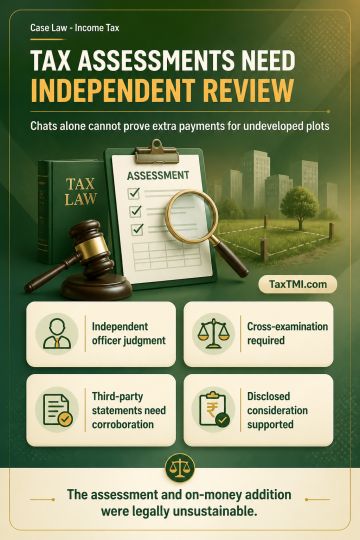
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
Page of 4897
Press 'Enter' after typing page number.
1621 to 1640 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Intra-group services closely linked to core business operations may be benchmarked together under TNMM; where facts and the business model remain unchanged, earlier transfer-pricing treatment should be followed despite pending departmental appeals. The related transfer-pricing adjustments and connected branch-office expenditure and depreciation/depletion disallowances were accordingly deleted or allowed. Arm's-length interest on external commercial borrowings required fresh determination by the AO/TPO. Site-restoration costs incurred to discharge a contractual decommissioning obligation were allowable business expenditure despite utilisation of a provision. Refund interest depended on verification of issuance and encashment; TDS credit required verification of corresponding income; and interest for filing and advance-tax defaults could not apply where withholding covered total tax liability.
Intra-group services closely linked to core business operations may be benchmarked together under TNMM; where facts and the business model remain unchanged, earlier transfer-pricing treatment should be followed despite pending departmental appeals. The related transfer-pricing adjustments and connected branch-office expenditure and depreciation/depletion disallowances were accordingly deleted or allowed. Arm's-length interest on external commercial borrowings required fresh determination by the AO/TPO. Site-restoration costs incurred to discharge a contractual decommissioning obligation were allowable business expenditure despite utilisation of a provision. Refund interest depended on verification of issuance and encashment; TDS credit required verification of corresponding income; and interest for filing and advance-tax defaults could not apply where withholding covered total tax liability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897