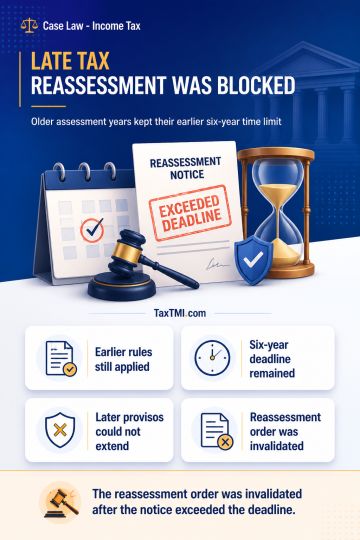
Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
Intra-group services closely linked to core business operations may be benchmarked together under TNMM; where facts and the business model remain unchanged, earlier transfer-pricing treatment should be followed despite pending departmental appeals. The related transfer-pricing adjustments and connected branch-office expenditure and depreciation/depletion disallowances were accordingly deleted or allowed. Arm's-length interest on external commercial borrowings required fresh determination by the AO/TPO. Site-restoration costs incurred to discharge a contractual decommissioning obligation were allowable business expenditure despite utilisation of a provision. Refund interest depended on verification of issuance and encashment; TDS credit required verification of corresponding income; and interest for filing and advance-tax defaults could not apply where withholding covered total tax liability.
Intra-group services closely linked to core business operations may be benchmarked together under TNMM; where facts and the business model remain unchanged, earlier transfer-pricing treatment should be followed despite pending departmental appeals. The related transfer-pricing adjustments and connected branch-office expenditure and depreciation/depletion disallowances were accordingly deleted or allowed. Arm's-length interest on external commercial borrowings required fresh determination by the AO/TPO. Site-restoration costs incurred to discharge a contractual decommissioning obligation were allowable business expenditure despite utilisation of a provision. Refund interest depended on verification of issuance and encashment; TDS credit required verification of corresponding income; and interest for filing and advance-tax defaults could not apply where withholding covered total tax liability.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927