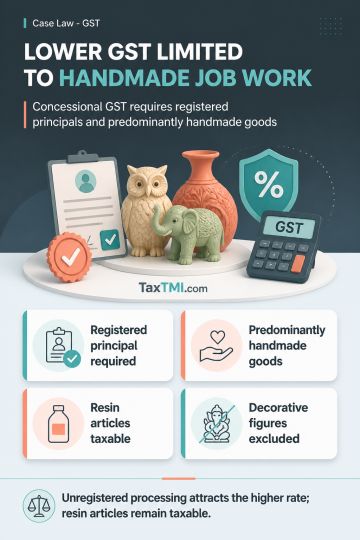
Handicraft job work receives concessional GST only for registered principals and predominantly handmade goods; commercial resin articles remain taxabl...
Reassessment disclosure requirements permit stated reasons without revealing information sources, but prior-taxation claims require full examination b...
Independent assessment discretion and corroborated electronic evidence determine validity of on-money additions and undisclosed-consideration assessme...
Page of 4897
Press 'Enter' after typing page number.
1621 to 1640 of 97923 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
AE segmental benchmarking under TNMM requires consideration of segmental results included in the transfer-pricing study and certified information furnished before completion of the transfer-pricing assessment. Neither the Act nor the Rules requires audited segmental accounts; where the AE-segment margin falls within the arm's-length range of selected comparables, rejection on conjectural grounds is unwarranted and the related adjustment is deleted. Ind AS presentation of part of compulsorily convertible debentures as equity does not change their underlying debt character before actual conversion or redemption. Interest remains deductible in principle, subject to verification that no conversion or redemption occurred during the relevant year.
AE segmental benchmarking under TNMM requires consideration of segmental results included in the transfer-pricing study and certified information furnished before completion of the transfer-pricing assessment. Neither the Act nor the Rules requires audited segmental accounts; where the AE-segment margin falls within the arm's-length range of selected comparables, rejection on conjectural grounds is unwarranted and the related adjustment is deleted. Ind AS presentation of part of compulsorily convertible debentures as equity does not change their underlying debt character before actual conversion or redemption. Interest remains deductible in principle, subject to verification that no conversion or redemption occurred during the relevant year.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897