Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Jurisdictional validity of revision notices: incorrect official capacity and mere change of opinion invalidate revision of property income assessments...
    MEIS export rewards are revenue income because they offset business costs rather than fund capital investment or expansion.
    TDS credit for trust income remains available despite trustee PAN reporting and absence of Rule 37BA declaration.
    Stale Reassessment Material Cannot Support Reopening When Earlier Proceedings Already Considered the Same Lender-Credit Information
    Block-period computation for non-searched persons rendered out-of-period assessments void for lack of jurisdiction under the search assessment regime.
    Sufficient Cause for Delay Requires Bona Fide Diligence, Leaving a Decade-Late Exemption Appeal Unheard on Merits
    Remand limitation periods require fresh-assessment timelines where Tribunal directions mandate fresh consideration, while unexplained foreign currency...
    Return-processing adjustments cannot tax validly applied accumulated charitable income merely because electronic return fields contain reporting misma...
    Cost of improvement excludes routine repairs and removable flat furnishings, while permanent installations require item-wise verification.
    Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
    Section 80G approval accepts section 10(23C) exemption without mandatory section 12AB registration, subject to verifying statutory coverage.
    Section 80G approval permits limited spiritual and satsang expenditure where the statutory religious-activity ceiling remains unbreached.
    Reassessment limitation renders post-expiry notices invalid, while missing scrutiny notice or improper approval defeats jurisdiction.
    Reasoned appellate adjudication requires merits-based decisions even where taxpayers do not prosecute appeals, requiring fresh disposal.
    Charitable accumulation rectification requires prior notice for return-processing adjustments and merits-based consideration of corrected audit report...
    Goods-description customs exemption covers MEG reclamation equipment for petroleum operations despite a different listed tariff heading.
    Post-clearance Bill of Entry amendments can enable preferential tariff reassessment upon later production of a retroactive certificate of origin.
    DIN deactivation requires notice, hearing and prescribed grounds; director disqualification alone does not automatically deactivate a DIN.
    CIRP closure despite infeasible statutory withdrawal is permitted after creditor settlements, with insolvency costs determined and paid separately.
    Personal guarantor insolvency cannot secure an interim moratorium solely to obstruct secured-asset enforcement without a genuine repayment plan.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Section 28(9A) of the Customs Act suspends the adjudication...

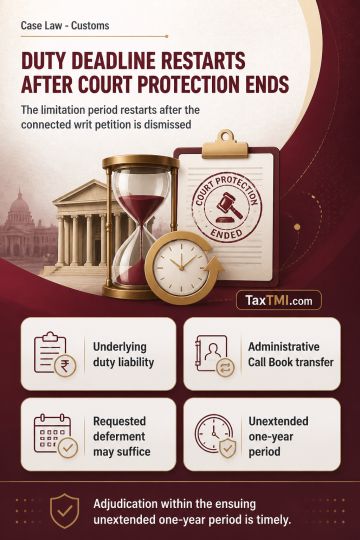
Interim stay exclusion under customs limitation begins when connected writ protection ends, preserving timely duty adjudication.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Customs September 9, 2026 Case Laws HC
Section 28(9A) of the Customs Act suspends the adjudication limitation period while a specified circumstance prevents determination of duty liability, with the statutory period recommencing when that circumstance ceases. Transfer of a matter to the Call Book is an administrative consequence of such deferment and does not independently create the exclusion period. Where noticees seek deferment because a connected writ petition and interim protection affect the underlying duty liability, those circumstances are directly relevant to non-determination. Noticees' own request for deferment may substantially satisfy the communication requirement. The limitation period consequently runs from dismissal of the connected writ petition, and adjudication within the ensuing unextended one-year period is timely.

Topics

Acts Income Tax