Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
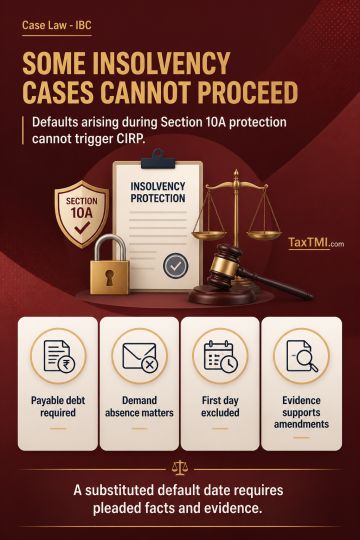
    Section 10A protection bars CIRP where cash-credit and ad hoc facility defaults arise during the protected period.
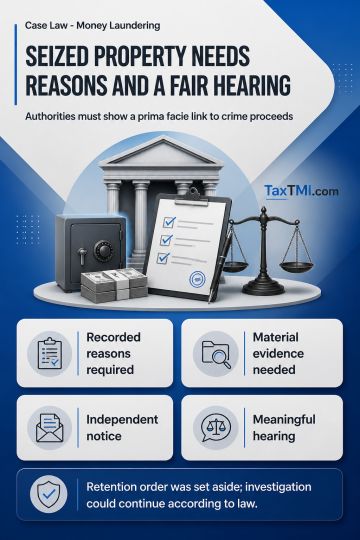
    PMLA retention safeguards require recorded reasons, evidentiary nexus and fair hearing; non-compliance invalidates continued seizure.
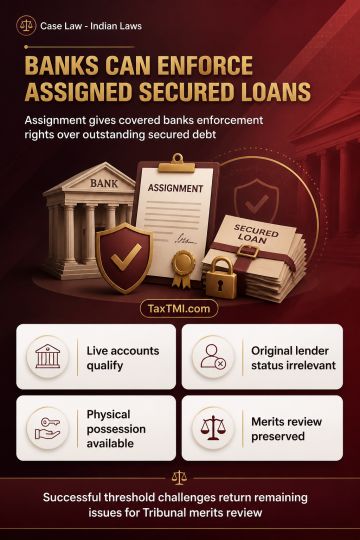
    Assigned secured debts permit banks to use SARFAESI, while borrowers retain merits review of remaining challenges before the Tribunal.
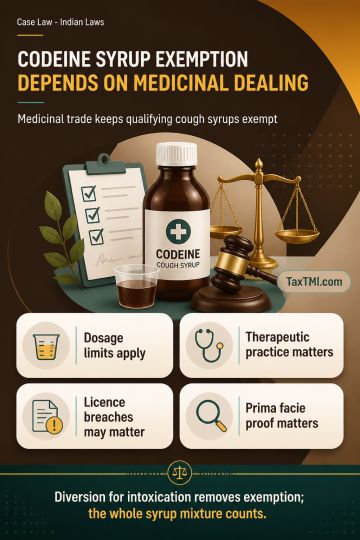
    Codeine cough syrup exemption turns on medicinal dealing, while intoxication diversion triggers NDPS liability and whole-mixture quantification.
    Input tax credit fraud permits Section 74 recovery where invoices and payments do not prove receipt of goods.
    PMLA anticipatory bail requires satisfaction of twin conditions, while predicate-offence protection does not extend to independent money-laundering pr...
    Sea cargo manifest compliance date is substituted in the Form XII table, effective upon Official Gazette publication.
    Raw sugar tariff-rate quota allocations move to daily batch processing, with pro-rata sharing when remaining quota is exhausted.
    Sea cargo manifest electronic filing becomes mandatory through phased port implementation, with no penalties during the transition period.
    Omission of GST refund restriction rule ends its application to proceedings pending on its omission date.
    Security-based bail conditions for alleged tax liabilities were modified when disclosed family assets could secure the alleged dues.
    Reasonable cause protects service-tax defaulters from Section 78 penalties when departmental guidance creates genuine interpretational uncertainty.
    GST refund restriction omission applies to pending proceedings, requiring related notices, orders and refund claims to be processed accordingly.
    Input tax credit for leased construction requires binding precedent consideration; unlawful ledger recovery must be reversed.
    Retrospective input tax credit protection overrides delayed-return limits, requiring reconsideration where statutory eligibility under Section 16(5) i...
    Electronic gift vouchers can validly pass GST rate-reduction benefits when unconditional, traceable e-wallet credits reach identified customers.
    School-affiliation charges remain taxable where not directly connected with examinations, while extended limitation requires proof of deliberate tax e...
    Finality of tax liability required before criminal prosecution may be closed; premature closure was set aside for reconsideration.
    Cash-basis deduction permits Work Contract Tax paid in the relevant year despite liability relating to earlier years.
    Abandoned expansion project costs qualify as revenue expenditure when no new enduring asset or distinct business emerges
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Advance Authorisation IGST exemption remains subject to the...

Pre-import condition breach under Advance Authorisation requires Bill of Entry-wise IGST reassessment, while interest and penalties fail.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Customs September 9, 2026 Case Laws AT
Advance Authorisation IGST exemption remains subject to the pre-import condition; later fulfilment of export obligation or issuance of EODCs does not erase an established breach. Imports breaching that condition must instead be regularised under the prescribed procedure, with EODCs and redemption certificates relevant to liability. IGST breach must be quantified Bill of Entry-wise and raw material-wise by correlating imports, exports and chronology, while accounting for permitted clubbing of authorisations. The IGST demand requires fresh quantification on that basis. For the relevant period, recovery provisions did not independently authorise interest, confiscation, redemption fine or penalty for the IGST liability; those consequential liabilities were set aside, including interest on re-quantified IGST.

Topics

Acts Income Tax