Clubbing of income from gifted property failed where the claim surfaced after reassessment limitation, sustaining capital-gains assessment in spouse's...
Employee stock-option discount qualifies as revenue expenditure, while royalty and service comparables require reliable functional and transactional b...
Special insurance income computation preserves statutory deductions while limiting transfer-pricing, withholding and disallowance adjustments for gene...
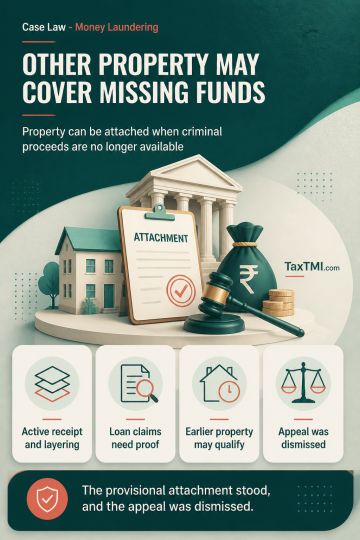
Confirmation of provisional attachment in money-laundering proceedings requires a prima facie showing of involvement; final criminal liability remains for trial. Communications, statements, cash-delivery arrangements, overseas transactions and recovered material may establish active receipt and layering of proceeds of crime, without reliance solely on a co-accused's statement. A person asserting that funds were a loan must substantiate that claim where the reverse burden applies. Where proceeds of crime are unavailable because they have vanished or been laundered, other property representing their value may be attached, including property acquired before the crime period. The provisional attachment was sustained and the appeal dismissed.
Confirmation of provisional attachment in money-laundering proceedings requires a prima facie showing of involvement; final criminal liability remains for trial. Communications, statements, cash-delivery arrangements, overseas transactions and recovered material may establish active receipt and layering of proceeds of crime, without reliance solely on a co-accused's statement. A person asserting that funds were a loan must substantiate that claim where the reverse burden applies. Where proceeds of crime are unavailable because they have vanished or been laundered, other property representing their value may be attached, including property acquired before the crime period. The provisional attachment was sustained and the appeal dismissed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4902