Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
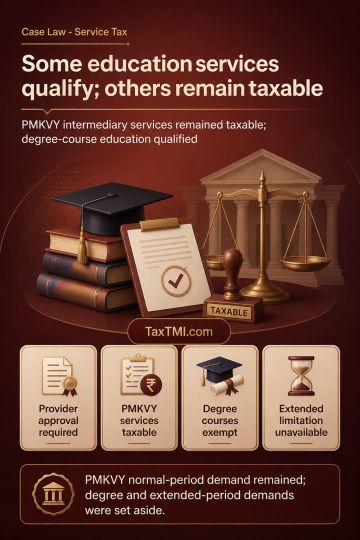
Service-tax exemption for NSDC skill-development programmes requires the provider itself to meet the notification's specified approval condition. An associate learning centre serving an NSDC-approved training partner did not qualify, so the normal-period demand relating to PMKVY services remained. Education connected with university degree courses qualified for the Negative List exemption where it formed part of a curriculum leading to a qualification recognised by law; direct provision by a university was not required, and that demand was set aside. Extended limitation was unavailable because wilful suppression with intent to evade was not established, resulting in deletion of the extended-period demand.
Service-tax exemption for NSDC skill-development programmes requires the provider itself to meet the notification's specified approval condition. An associate learning centre serving an NSDC-approved training partner did not qualify, so the normal-period demand relating to PMKVY services remained. Education connected with university degree courses qualified for the Negative List exemption where it formed part of a curriculum leading to a qualification recognised by law; direct provision by a university was not required, and that demand was set aside. Extended limitation was unavailable because wilful suppression with intent to evade was not established, resulting in deletion of the extended-period demand.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881