Restricted gold import conditions: breach permits absolute confiscation, while redemption remains discretionary and is rarely disturbed on writ review...
Bail conditions in customs-duty evasion investigation permit continued inquiry while addressing evidence-tampering concerns through procedural safegua...
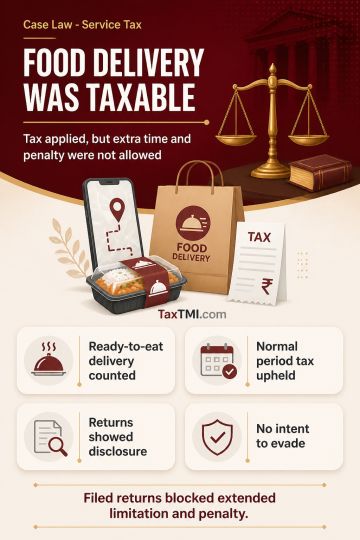
Free home delivery of ready-to-eat food, involving preparation at the supplier's premises and delivery at a customer-specified time and place, was treated as a taxable service with a significant service element. From July 2012, supplying food for human consumption in this manner fell within declared services and also within the earlier concept of outdoor catering. Service tax was consequently sustainable for the normal limitation period. The extended limitation period and related penalty were not sustainable because the supplier was registered, filed ST-3 returns, paid service tax, and the allegations arose from its own records, with no evidence of suppression intended to evade tax.
Free home delivery of ready-to-eat food, involving preparation at the supplier's premises and delivery at a customer-specified time and place, was treated as a taxable service with a significant service element. From July 2012, supplying food for human consumption in this manner fell within declared services and also within the earlier concept of outdoor catering. Service tax was consequently sustainable for the normal limitation period. The extended limitation period and related penalty were not sustainable because the supplier was registered, filed ST-3 returns, paid service tax, and the allegations arose from its own records, with no evidence of suppression intended to evade tax.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881