Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
Appealability of Tribunal directions under Rule 41 is limited: a...
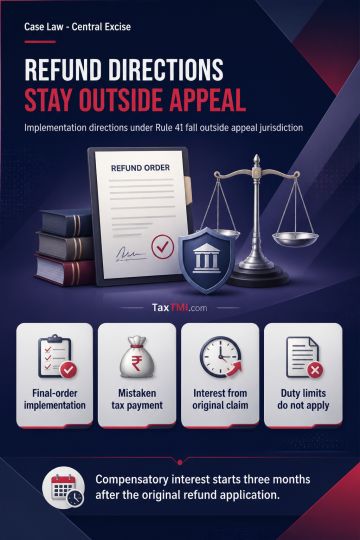
Rule 41 implementation directions remain outside appellate review, while mistaken service-tax payments attract compensatory interest from the original refund claim.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Appealability of Tribunal directions under Rule 41 is limited: a procedural or implementation direction intended to give effect to a final order is not an order passed in appeal and falls outside Section 35G appellate jurisdiction. Rule 41 permits consequential directions, including compensatory interest, where necessary to implement a final refund order. Service tax paid for laying potable-water pipelines for a State agency's public-welfare project was treated as paid under a mistake of law rather than as duty, displacing duty-refund limitation requirements. Interest runs from three months after the original refund application, not later supporting documents; statutory delayed-duty refund rate limits do not govern compensatory interest.
Appealability of Tribunal directions under Rule 41 is limited: a procedural or implementation direction intended to give effect to a final order is not an order passed in appeal and falls outside Section 35G appellate jurisdiction. Rule 41 permits consequential directions, including compensatory interest, where necessary to implement a final refund order. Service tax paid for laying potable-water pipelines for a State agency's public-welfare project was treated as paid under a mistake of law rather than as duty, displacing duty-refund limitation requirements. Interest runs from three months after the original refund application, not later supporting documents; statutory delayed-duty refund rate limits do not govern compensatory interest.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881