Road restoration charges constitute taxable services when requested for commercial pipeline activity, requiring reverse-charge GST from the business r...
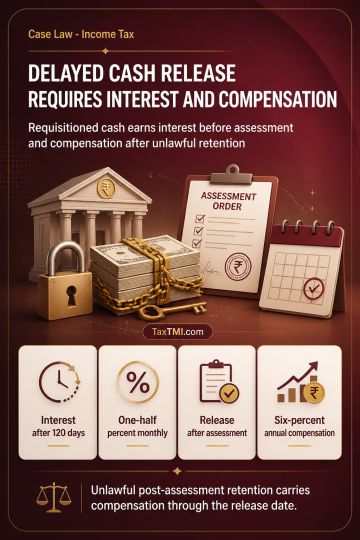
Interest on delayed release of requisitioned cash includes statutory pre-assessment interest and restitutionary compensation for unlawful post-assessm...
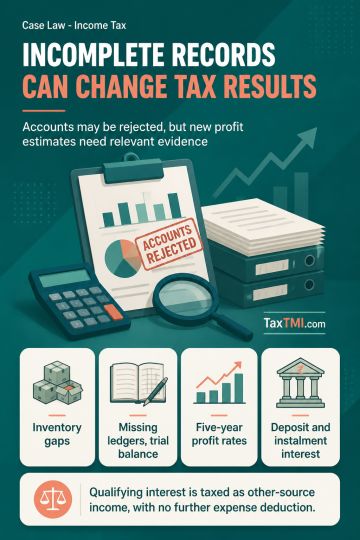
Incomplete inventory records justify rejecting accounts, while profit estimation requires relevant comparable material and interest falls under other ...
Transfer-pricing comparability requires functional alignment; delayed associated-enterprise receivables need separate LIBOR-based benchmarking, while ...
Extended reassessment limitation in search cases requires asset-linked escaped income, invalidating additions based only on unexplained money or expen...
Enhanced tolerance band under section 43CA applies retrospectively, deleting qualifying deemed-sale additions while disputed stamp valuation requires ...
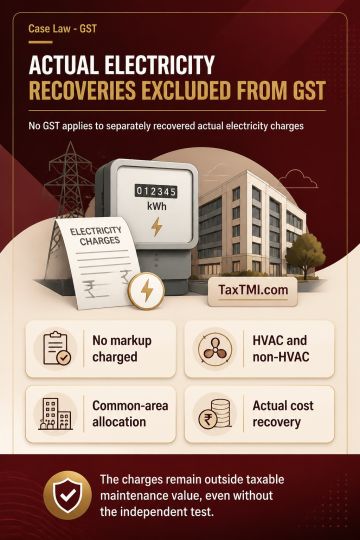
Actual electricity charges separately recovered at the same amount charged by the electricity distribution company, without markup, are treated as pure-agent recoveries under clause 3.3 of Circular No. 206/18/2023-GST. Electricity supplied with premises maintenance is ordinarily ancillary to the maintenance service and forms part of a composite supply despite separate billing. The circular's deeming rule nevertheless applies to separately metered HVAC and non-HVAC consumption and proportionately allocated common-area consumption recovered at actual cost. Those recoveries are excluded from the value of the maintenance service and do not attract GST, even where the independent pure-agent test is not otherwise met.
Actual electricity charges separately recovered at the same amount charged by the electricity distribution company, without markup, are treated as pure-agent recoveries under clause 3.3 of Circular No. 206/18/2023-GST. Electricity supplied with premises maintenance is ordinarily ancillary to the maintenance service and forms part of a composite supply despite separate billing. The circular's deeming rule nevertheless applies to separately metered HVAC and non-HVAC consumption and proportionately allocated common-area consumption recovered at actual cost. Those recoveries are excluded from the value of the maintenance service and do not attract GST, even where the independent pure-agent test is not otherwise met.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935