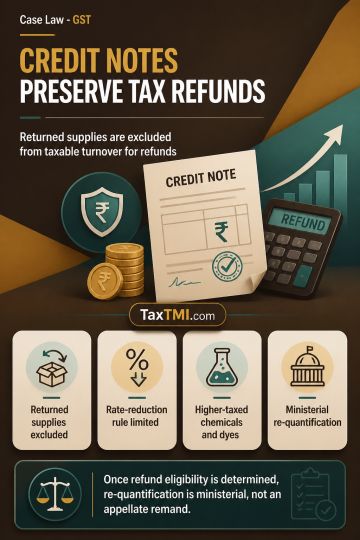
Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
For a non-searched person, the block period for assessment under section 153C is computed from the date seized material is handed over to, or satisfaction is recorded by, the Assessing Officer having jurisdiction over that person, rather than from the search date. Applying that rule, the relevant assessment years fell outside the permissible period, making the assessments time-barred and depriving the Assessing Officer of valid jurisdiction. ITAT upheld the relief granted to the non-searched person and dismissed the Revenue's appeals, following Supreme Court and High Court precedent.
For a non-searched person, the block period for assessment under section 153C is computed from the date seized material is handed over to, or satisfaction is recorded by, the Assessing Officer having jurisdiction over that person, rather than from the search date. Applying that rule, the relevant assessment years fell outside the permissible period, making the assessments time-barred and depriving the Assessing Officer of valid jurisdiction. ITAT upheld the relief granted to the non-searched person and dismissed the Revenue's appeals, following Supreme Court and High Court precedent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4935