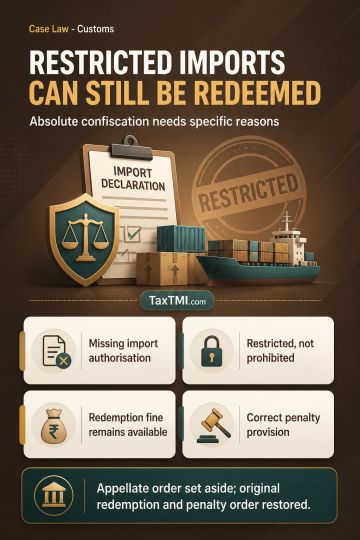
Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
For a non-searched person, the block period for assessment under section 153C is computed from the date seized material is handed over to, or satisfaction is recorded by, the Assessing Officer having jurisdiction over that person, rather than from the search date. Applying that rule, the relevant assessment years fell outside the permissible period, making the assessments time-barred and depriving the Assessing Officer of valid jurisdiction. ITAT upheld the relief granted to the non-searched person and dismissed the Revenue's appeals, following Supreme Court and High Court precedent.
For a non-searched person, the block period for assessment under section 153C is computed from the date seized material is handed over to, or satisfaction is recorded by, the Assessing Officer having jurisdiction over that person, rather than from the search date. Applying that rule, the relevant assessment years fell outside the permissible period, making the assessments time-barred and depriving the Assessing Officer of valid jurisdiction. ITAT upheld the relief granted to the non-searched person and dismissed the Revenue's appeals, following Supreme Court and High Court precedent.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881