Capital-gains exemption for charitable trusts extends to qualifying fixed deposits, while unrecoverable TDS write-offs may constitute income applicati...
India-UK treaty characterisation of telecom-service receipts as business profits withstands unilateral domestic-law amendments for Indian tax purposes...
Transfer-pricing reimbursement adjustments require uncontrolled comparables and cannot become expense-genuineness reviews, resulting in deletion of th...
Food import sampling requirements support provisional release where unseized consignments conform to standards and raw areca classification is unestab...
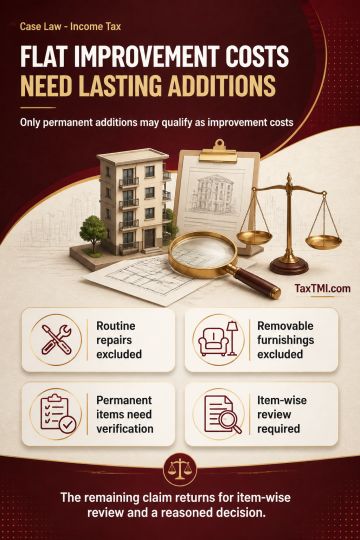
Cost of improvement of a residential flat requires capital expenditure that adds to or alters the capital asset. Routine repairs and removable articles, including furnishings and de cor not embedded in the property, merely remain associated with the flat and do not qualify; their disallowance was sustained. The description assigned to an item is not conclusive for alleged permanent installations. Their eligibility depends on whether each item is capital in nature and forms an integral addition or alteration to the flat. As the installation and nature of the remaining items had not been examined item-wise, the claim was restored for verification of supporting material and a reasoned determination after hearing the taxpayer.
Cost of improvement of a residential flat requires capital expenditure that adds to or alters the capital asset. Routine repairs and removable articles, including furnishings and de cor not embedded in the property, merely remain associated with the flat and do not qualify; their disallowance was sustained. The description assigned to an item is not conclusive for alleged permanent installations. Their eligibility depends on whether each item is capital in nature and forms an integral addition or alteration to the flat. As the installation and nature of the remaining items had not been examined item-wise, the claim was restored for verification of supporting material and a reasoned determination after hearing the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4932