Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
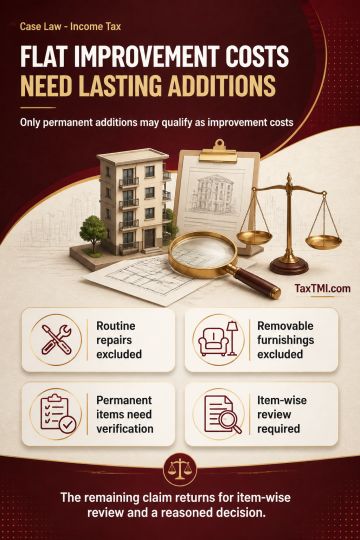
Cost of improvement of a residential flat requires capital expenditure that adds to or alters the capital asset. Routine repairs and removable articles, including furnishings and de cor not embedded in the property, merely remain associated with the flat and do not qualify; their disallowance was sustained. The description assigned to an item is not conclusive for alleged permanent installations. Their eligibility depends on whether each item is capital in nature and forms an integral addition or alteration to the flat. As the installation and nature of the remaining items had not been examined item-wise, the claim was restored for verification of supporting material and a reasoned determination after hearing the taxpayer.
Cost of improvement of a residential flat requires capital expenditure that adds to or alters the capital asset. Routine repairs and removable articles, including furnishings and de cor not embedded in the property, merely remain associated with the flat and do not qualify; their disallowance was sustained. The description assigned to an item is not conclusive for alleged permanent installations. Their eligibility depends on whether each item is capital in nature and forms an integral addition or alteration to the flat. As the installation and nature of the remaining items had not been examined item-wise, the claim was restored for verification of supporting material and a reasoned determination after hearing the taxpayer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881