Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
Where purchases are obtained through accommodation-entry...
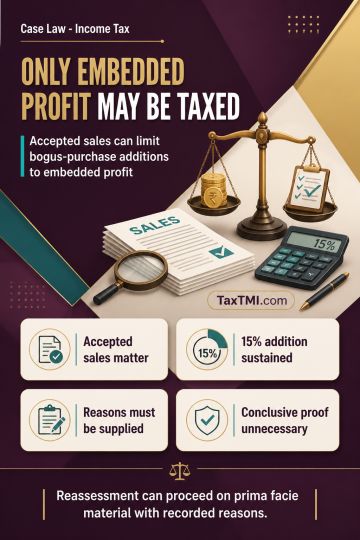
Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reassessment.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Where purchases are obtained through accommodation-entry providers but corresponding sales remain undisputed, taxation is confined to the profit element embedded in those purchases rather than the entire purchase value. In comparable bogus-purchase transactions, an addition of 15% of the impugned purchases was sustained. Reassessment based on accommodation-entry information is valid where the Assessing Officer supplies recorded reasons, disposes of objections, and possesses prima facie material with a live link to the belief that income escaped assessment. At the reopening stage, the material need not be conclusive; its sufficiency is not examined.
Where purchases are obtained through accommodation-entry providers but corresponding sales remain undisputed, taxation is confined to the profit element embedded in those purchases rather than the entire purchase value. In comparable bogus-purchase transactions, an addition of 15% of the impugned purchases was sustained. Reassessment based on accommodation-entry information is valid where the Assessing Officer supplies recorded reasons, disposes of objections, and possesses prima facie material with a live link to the belief that income escaped assessment. At the reopening stage, the material need not be conclusive; its sufficiency is not examined.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881