Permanent-establishment reassessment cannot revisit scrutinised disclosures; extended reopening fails without undisclosed material facts and within st...
Modified returns after business reorganisation must be assessed within pending proceedings, barring parallel scrutiny and consequential transfer prici...
Turnover mismatches under percentage-completion accounting cannot alone establish suppressed income where customer advances remain recorded as liabili...
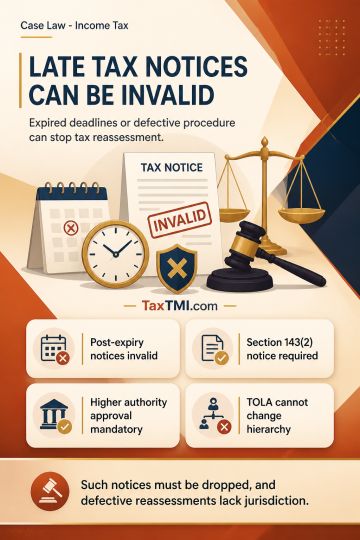
Reassessment notices for AY 2015-16 issued on or after 1 April 2021 were required to be dropped because the extended period did not preserve the power to issue fresh notices after limitation expired. Reassessment is also without jurisdiction where a return filed in response to a reassessment notice before completion is treated as non-existent solely because it was belated and no notice under section 143(2) is issued. For reopening beyond three years, prior approval from the higher specified authority is mandatory; TOLA's time extension does not alter the statutory hierarchy, making approval by the Principal Commissioner insufficient.
Reassessment notices for AY 2015-16 issued on or after 1 April 2021 were required to be dropped because the extended period did not preserve the power to issue fresh notices after limitation expired. Reassessment is also without jurisdiction where a return filed in response to a reassessment notice before completion is treated as non-existent solely because it was belated and no notice under section 143(2) is issued. For reopening beyond three years, prior approval from the higher specified authority is mandatory; TOLA's time extension does not alter the statutory hierarchy, making approval by the Principal Commissioner insufficient.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4927