Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
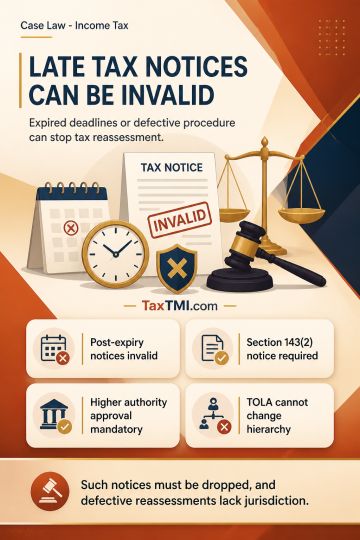
Reassessment notices for AY 2015-16 issued on or after 1 April 2021 were required to be dropped because the extended period did not preserve the power to issue fresh notices after limitation expired. Reassessment is also without jurisdiction where a return filed in response to a reassessment notice before completion is treated as non-existent solely because it was belated and no notice under section 143(2) is issued. For reopening beyond three years, prior approval from the higher specified authority is mandatory; TOLA's time extension does not alter the statutory hierarchy, making approval by the Principal Commissioner insufficient.
Reassessment notices for AY 2015-16 issued on or after 1 April 2021 were required to be dropped because the extended period did not preserve the power to issue fresh notices after limitation expired. Reassessment is also without jurisdiction where a return filed in response to a reassessment notice before completion is treated as non-existent solely because it was belated and no notice under section 143(2) is issued. For reopening beyond three years, prior approval from the higher specified authority is mandatory; TOLA's time extension does not alter the statutory hierarchy, making approval by the Principal Commissioner insufficient.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881