Bogus-purchase additions are limited to embedded profit where corresponding sales are accepted, while accommodation-entry information can support reas...
Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Page of 4937
Press 'Enter' after typing page number.
2121 to 2140 of 98735 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
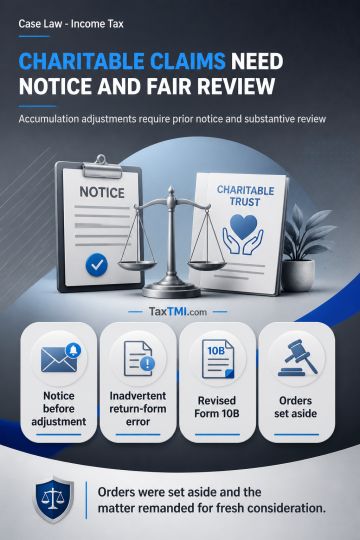
Return-processing adjustments to a charitable accumulation claim require compliance with the first proviso to section 143(1A), including an opportunity before the adjustment is made. Non-compliance vitiated the adjustment. Where an assessee's accumulated amount was incorrectly reported through an inadvertent return-form error, supported by an indemnity bond and a revised Form 10B, rectification required substantive consideration rather than rejection solely on a technical basis. The processing and rectification orders were set aside and remanded for consideration of the revised audit report, determination of correct income, and grant of admissible relief.
Return-processing adjustments to a charitable accumulation claim require compliance with the first proviso to section 143(1A), including an opportunity before the adjustment is made. Non-compliance vitiated the adjustment. Where an assessee's accumulated amount was incorrectly reported through an inadvertent return-form error, supported by an indemnity bond and a revised Form 10B, rectification required substantive consideration rather than rejection solely on a technical basis. The processing and rectification orders were set aside and remanded for consideration of the revised audit report, determination of correct income, and grant of admissible relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4937