Concessional penalty for search-disclosed unreconciled jewellery applies where substantive disclosure conditions are met despite omission from origina...
Alternative statutory remedy and unexplained delay barred writ review of customs confiscation adjudication, leaving merits for appellate consideration...
Page of 4888
Press 'Enter' after typing page number.
1261 to 1280 of 97755 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
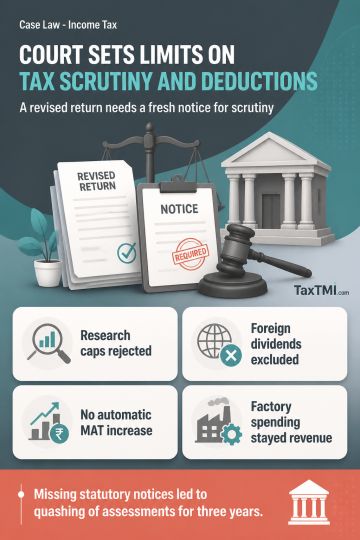
Scrutiny assessments founded on revised returns require a statutory notice tied to the operative revised return; its absence is an incurable jurisdictional defect not cured by participation, and assessments for three years were quashed. Pre-amendment annual Form 3CL quantification could not defeat or cap weighted research-and-development deductions where substantive approval existed, but eligibility required limited verification. Rule 8D disallowance required account-based satisfaction, excluded investments yielding taxable foreign dividends, and could not automatically increase book profit under the self-contained minimum alternate tax regime. Expenditure improving access to an existing factory remained revenue expenditure where no capital asset or proprietary advantage was acquired.
Scrutiny assessments founded on revised returns require a statutory notice tied to the operative revised return; its absence is an incurable jurisdictional defect not cured by participation, and assessments for three years were quashed. Pre-amendment annual Form 3CL quantification could not defeat or cap weighted research-and-development deductions where substantive approval existed, but eligibility required limited verification. Rule 8D disallowance required account-based satisfaction, excluded investments yielding taxable foreign dividends, and could not automatically increase book profit under the self-contained minimum alternate tax regime. Expenditure improving access to an existing factory remained revenue expenditure where no capital asset or proprietary advantage was acquired.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888