Business expenditure and depreciation rules allow operational outgoings while limiting disallowances for personal elements and unsupported third-party...
Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
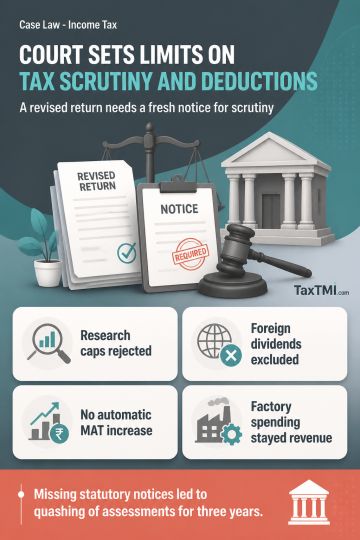
Scrutiny assessments founded on revised returns require a statutory notice tied to the operative revised return; its absence is an incurable jurisdictional defect not cured by participation, and assessments for three years were quashed. Pre-amendment annual Form 3CL quantification could not defeat or cap weighted research-and-development deductions where substantive approval existed, but eligibility required limited verification. Rule 8D disallowance required account-based satisfaction, excluded investments yielding taxable foreign dividends, and could not automatically increase book profit under the self-contained minimum alternate tax regime. Expenditure improving access to an existing factory remained revenue expenditure where no capital asset or proprietary advantage was acquired.
Scrutiny assessments founded on revised returns require a statutory notice tied to the operative revised return; its absence is an incurable jurisdictional defect not cured by participation, and assessments for three years were quashed. Pre-amendment annual Form 3CL quantification could not defeat or cap weighted research-and-development deductions where substantive approval existed, but eligibility required limited verification. Rule 8D disallowance required account-based satisfaction, excluded investments yielding taxable foreign dividends, and could not automatically increase book profit under the self-contained minimum alternate tax regime. Expenditure improving access to an existing factory remained revenue expenditure where no capital asset or proprietary advantage was acquired.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4886