Prospective customs notification amendments cannot bar provisional release consideration for earlier imports when bills of lading predate their commen...
Personal guarantor insolvency jurisdiction follows the corporate debtor's CIRP Bench, enabling inter-territorial transfer and preventing parallel proc...
Section 47-A undervaluation threshold: fraudulent intent requirement faces reconsideration after referral to a larger Bench for authoritative resoluti...
RBI supersession powers over multi-State co-operative banks operate independently of the constitutional six-month ceiling and permit statutory extensi...
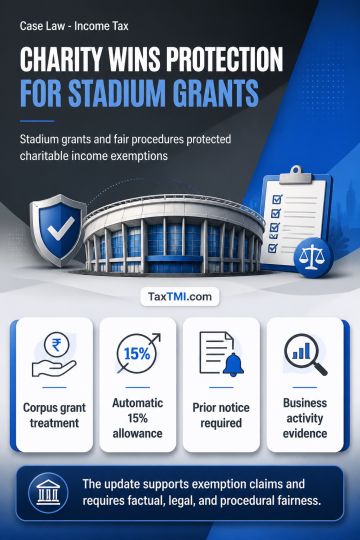
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4897