Compromise-and-arrangement extensions may accommodate debt assignment where creditor commercial judgment supports value maximisation and avoids proced...
Delayed-payment surcharge is not taxable tolerance consideration where it penalises default, while meter testing follows electricity distribution trea...
Sufficient cause for delayed revenue income-tax appeals requires bona fides, due diligence and a credible explanation; otherwise limitation bars appea...
Inverted-duty-structure refunds remain available for unchanged-rate apparel supplies despite trader status and require tax-period-specific computation...
Foundational assessment satisfaction is essential before initiating penalty for cash receipt of immovable-property sale consideration under section 27...
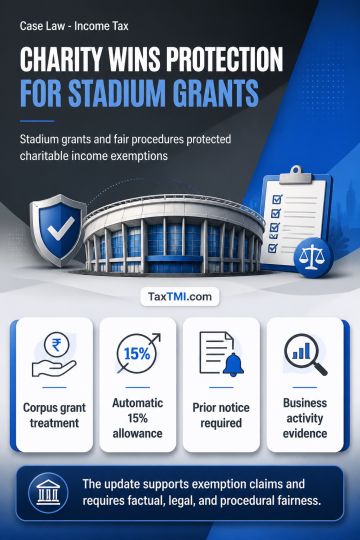
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4888