Coercive recovery during GST searches is restrained pending scrutiny, preserving normal business operations and requiring adherence to investigation g...
COVID-19 limitation exclusion and destination-specific e-way bills govern revisional timelines and penalties for undocumented third-party plywood deli...
Questions arising from miscellaneous application orders cannot challenge unaltered Tribunal findings, leaving the original order separately challengea...
Transfer-pricing comparability filters require fresh arm's-length analysis, while delayed receivables need separate reconsideration with working-capit...
Page of 4894
Press 'Enter' after typing page number.
721 to 740 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
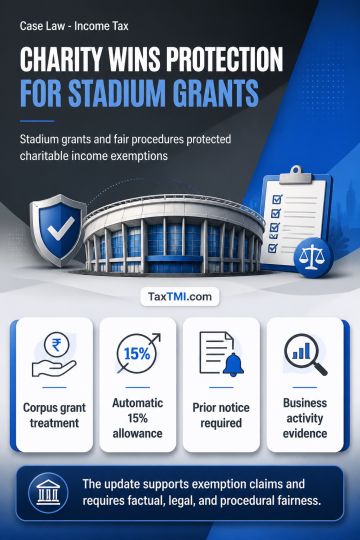
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Infrastructure grants expressly earmarked for stadium construction, credited to a corpus fund and applied for that purpose qualify as corpus donations exempt under section 11(1)(d). Accumulation under section 11(2) cannot be denied solely for delayed Form No. 10 filing where condonation was sought before assessment and subsequent relief applies. The statutory 15% accumulation under section 11(1)(a) is automatic and does not depend on Form No. 10. Additions made without a show-cause notice violate natural justice. A cricket association's activities do not attract the commercial-activity proviso absent evidence of trade, commerce or business. Depreciation, unspecified section 13 allegations and unsupported receipt enhancements require a factual and legal basis.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894