Provisional attachment fails without material showing likely concealment, transfer, or dealing that could frustrate confiscation of mortgaged property...
Works-contract goods transfers remain outside service tax, while qualifying lift irrigation works receive exemption and extended limitation cannot app...
Customs assessment information portal centralises rulings and guidance to promote consistent classification, valuation, transparency and informed comp...
Composite show-cause notices spanning multiple financial years are jurisdictionally invalid, allowing writ review despite an alternative appellate rem...
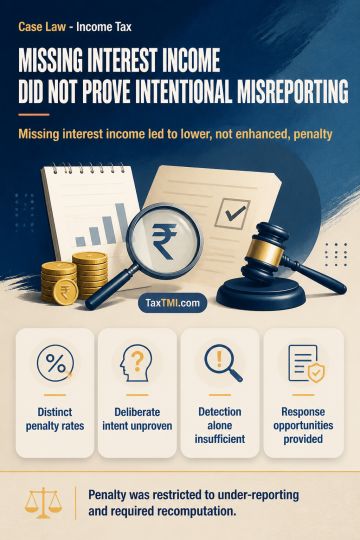
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4881