Income-tax prosecution fails when appellate remand removes its factual foundation; directors require company arraignment for vicarious criminal liabil...
Capital character of assignment consideration prevents taxation as residuary income, while unsupported interest-related expenditure remains non-deduct...
Make-available condition shields regional support-service receipts from Indian taxation where no independent capability or permanent establishment exi...
Transfer-pricing treatment of corporate guarantees and convertible loans followed prior-year consistency, with taxable foreign dividends excluded from...
Transfer-pricing benchmarking confines adjustments to associated-enterprise transactions and integrates delayed receivables through TNMM working-capit...
Medical relief status protects government-contracted mobile healthcare from commercial classification, while provisional registration cancellation req...
Charitable registration cancellation requires proof that educational activities abandoned their objects; incidental receipts and retained surplus are ...
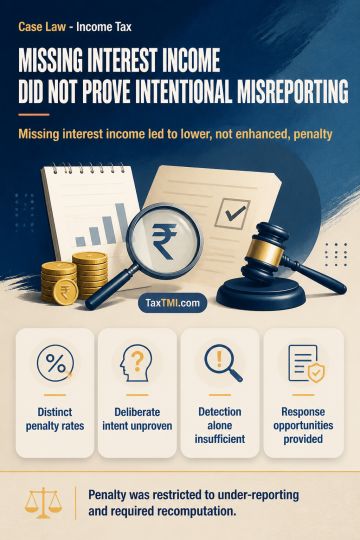
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4884