Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
Final benami adjudication bars contradictory tax-evasion prosecution where settlement findings confirm full disclosure and cooperation without conceal...
Faceless assessment and registration procedures are updated through electronic communication, revised recovery rules, extended deadlines, and replacem...
Risk-based selective vessel boarding requires accurate declarations and preserves master and agent liability where physical inspections are not select...
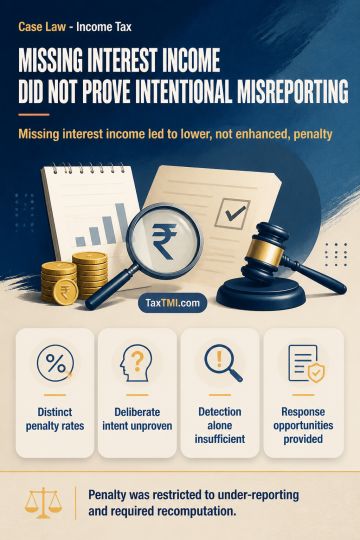
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4891