Actual-user customs exemption conditions permit turnkey project transfers when imported windmill components are exclusively used for installation and ...
Customs offence disqualification excludes civil contraventions, preventing refusal of a private bonded warehouse licence based solely on monetary pena...
Residual food-preparation classification places fermented Nata De Coco outside fruit-jelly categories, changing its GST treatment across notified peri...
Page of 4894
Press 'Enter' after typing page number.
661 to 680 of 97867 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
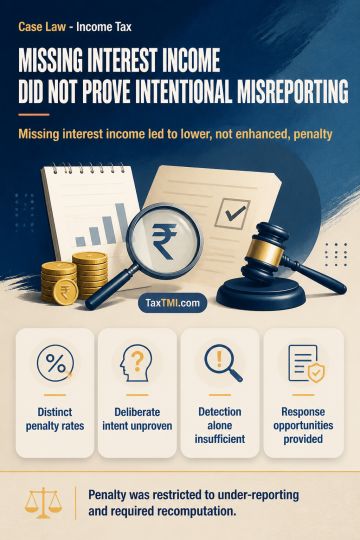
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Under-reporting and misreporting of income attract distinct penalty treatment: under-reporting is penalised at 50% of the tax payable, while under-reporting resulting from misreporting attracts 200% only where specified factual circumstances establish misreporting. Omission of interest income constituted under-reporting, but non-resident status, reliance on an accountant, limited technological knowledge, and later payment of tax and interest did not establish deliberate misreporting. Departmental detection and non-response to notices alone were insufficient for the enhanced penalty. The penalty was therefore restricted to under-reporting, with recomputation. Statutory and show-cause notices, along with opportunities to respond during penalty proceedings, satisfied hearing requirements where the taxpayer did not use those opportunities.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4894