Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Income Tax
  • Direct Taxes
  • Benami Property
  • Central GST Laws
  • SGST - State GST Laws
  • Customs
  • FTP - Foreign Trade Policy
  • SEZ - Special Economic Zone
  • FEMA - Foreign Exchange Management
  • Companies Law
  • SEBI - Securities & Exchange Board of India
  • IBC - Insolvency and Bankruptcy
  • Law of Competition
  • PMLA - Money-Laundering
  • Indian Laws
  • Bill / Finance Bills
  • Wealth Tax
  • Service Tax
  • Central Excise
  • VAT / Sales Tax
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    Assessment Transfer Without Statutory Authority Nullifies Transferee Assessment and Consequential Penalty for Inaccurate Income Particulars
    Corpus Donations and Charitable Accumulation: Cricket infrastructure grants and procedural fairness protect charitable income exemptions
    Misreporting penalties require proven statutory circumstances; omitted interest income attracts under-reporting treatment absent evidence of deliberat...
    Bona fide disclosed legal claims on slump-sale negative net worth do not constitute inaccurate particulars for penalty purposes.
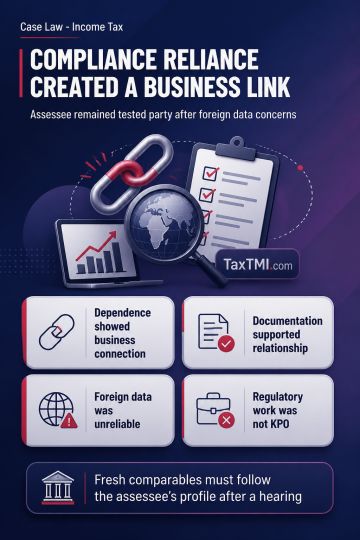
    Business Dependence Establishes Associated Enterprise Status; Domestic Tested Party and Fresh Regulatory Affairs Benchmarking Required
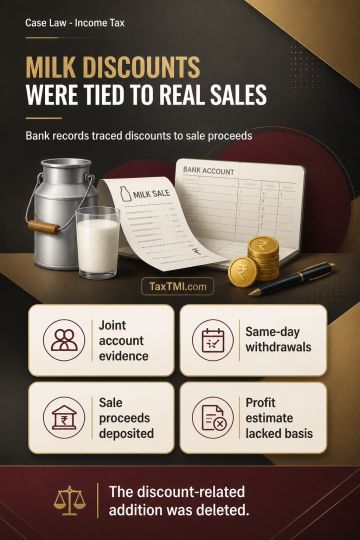
    Trade discounts received by milk resale agents are explained income, preventing estimated additions as unexplained money.
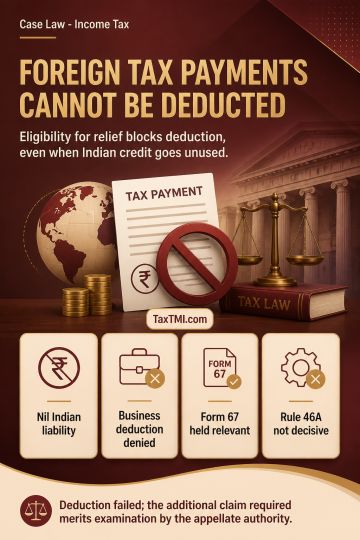
    Foreign withholding tax remains non-deductible where eligible for double-taxation relief, even if no Indian credit is usable.
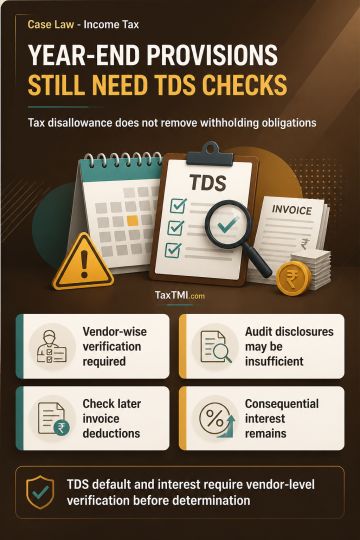
    Year-end expense provisions require independent TDS compliance despite tax disallowance, subject to vendor-level verification of withholding liability...
    Reverse burden for foreign-marked gold requires traceable proof, while unlinked silver and cash cannot be confiscated.
    Writ jurisdiction cannot order release of detained gold when alleged Customs notice breaches require resolving disputed facts.
    Alternative statutory revision governs baggage confiscation disputes where notice waiver and document voluntariness require factual examination.
    Clinical trial testing exemption covers sponsor-approved CRO services; employee bond forfeitures are not taxable training consideration.
    Reassessment-Based Export Duty Refund Limitation Starts When Excess Payment Becomes Ascertainable, With Interest Following the Statutory Refund Period
    Customs officer appointment validates DRI recovery notices while penalties stand for admitted participation in prohibited-goods smuggling conspiracy.
    Extended limitation fails where departmental knowledge defeats suppression, while pile-fabric classification stands and exemption claims require merit...
    Restricted second-hand goods remain redeemable when absolute confiscation lacks specific reasons, and penalties must follow the applicable import prov...
    Section 213(b) investigation safeguards require recorded satisfaction and prior hearing before agencies are asked for tracking information.
    Going-concern liquidation sales support consequential implementation reliefs but cannot override auction terms, statutory compliance, or ungranted con...
    Anticipatory bail in money-laundering matters requires scrutiny of arrest necessity and is refused where prima facie involvement exists.
    Equivalent-value attachment requires an established money trail and a genuine risk of frustrating confiscation proceedings.
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Highlights
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries

Highlights

Back

All Highlights

Showing Results for :
Reset Filters
No Records Found

Highlights

Back

All Highlights

Penalty under section 271(1)(c) is not leviable where a taxpayer...

Bona fide disclosed legal claims on slump-sale negative net worth do not constitute inaccurate particulars for penalty purposes.

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Income Tax September 7, 2026 Case Laws AT
Penalty under section 271(1)(c) is not leviable where a taxpayer fully discloses a slump-sale transaction, consideration and negative net worth, but computes capital gains by treating negative net worth as nil on a bona fide legal interpretation. A claim that is ultimately unsustainable does not amount to furnishing inaccurate particulars merely because a quantum addition is sustained or not contested. Divergent Tribunal views and admission of a substantial question of law support the conclusion that the treatment of negative net worth was genuinely debatable. The penalty deletion was sustained and the Revenue's appeal failed.

Topics

Acts Income Tax